2-1 Buydown vs. Permanent Buydown: Which Wins at 7% Rates?
2-1 Buydown vs. Permanent Buydown: Which One Makes Sense When Rates Top 7%?By Chad Anderson · October 5, 2026 Mortgage rates just had their biggest one-week jump since 2022. Freddie Mac's 30-year average hit 7.28% on October 1, up from 7.03% the week before. When rates climb like that, one phrase starts showing up in every builder ad and listing description: "rate buydown available." That can be a great deal. It can also be a nice-sounding offer that doesn't do much for you. The difference usually comes down to which kind of buydown it is, and how long you plan to keep the loan. WHAT A BUYDOWN ACTUALLY ISA buydown is money paid upfront to lower your interest rate. Most of the time, the seller or builder pays it as part of the deal. There are two kinds. A temporary buydown lowers your rate for the first year or two. The most common version is the 2-1 buydown: your rate is 2% lower in year one, 1% lower in year two, then goes to the full rate for the rest of the loan. A permanent buydown lowers your rate for the life of the loan. You'll hear these called "points." You pay more upfront, and the lower rate never goes away. THE 2-1 BUYDOWN IN REAL NUMBERSHere's what a 2-1 buydown looks like at today's 7.28% average with 5% down on a conventional loan, using the August median prices in both of our local markets. 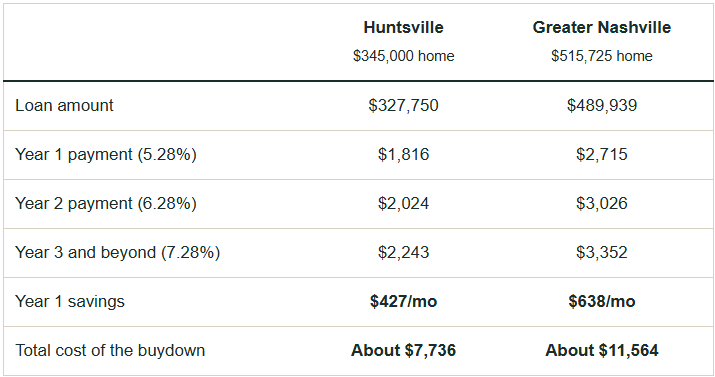 THE PART MOST PEOPLE MISSYou qualify at the full rate. The lender looks at your year-three payment, not your year-one payment. A 2-1 buydown doesn't help you afford more house. It just makes the first two years easier. Year three is coming either way. If rates drop, you may be able to refinance. If they don't, you're at the full payment. I never want a buyer counting on a refinance to make a house affordable. Refinancing is a bonus, not a plan. HOW TO COMPARE IT TO A PERMANENT BUYDOWNNow take the same money and use it to permanently lower your rate. How far it moves your rate depends on lender pricing that day, so you need a real quote. But the comparison works the same way every time. Here's an illustration. Say the Huntsville buyer's $7,736 could permanently lower the rate from 7.28% to 6.78%. The payment would drop about $110 a month, for all 30 years. After two years: the 2-1 buydown has paid back the full $7,736. The permanent buydown has paid back about $2,645. After about six years: the permanent buydown catches up. Every month after that, it keeps saving you money while the temporary one is long gone. 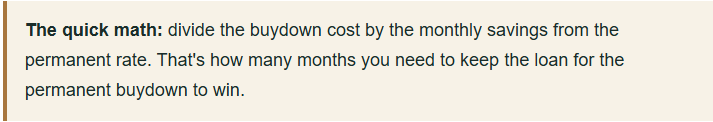 THREE QUESTIONS THAT DECIDE IT1. How long will you keep this loan? Planning to stay put and keep the mortgage for years? Permanent usually wins. Expect to move, or think there's a good chance you'll refinance soon? The 2-1 front-loads the savings. 2. Can you comfortably afford the full payment today? If the year-three payment makes you nervous, a temporary buydown is just delaying the problem. Look at a lower price range instead. 3. Do you need cash more than a lower payment? Sometimes the smartest use of seller money is covering closing costs so you keep your savings intact. A slightly higher payment beats an empty emergency fund. NASHVILLE VS. HUNTSVILLE: WHERE YOU CAN ASK FOR ITSeller money depends on leverage, and our two markets are in very different places right now. Greater Nashville had about five months of supply in August, with inventory up 7% from last year and sales down 4%. Sellers and builders have more reason to deal. Asking for a buydown or closing cost help is reasonable on a lot of homes. Huntsville had about 3.7 months of supply, with sales up 10% and homes selling in 42 days on average. Well-priced homes in good areas still move quickly. Concessions are still possible, especially with builders and on homes that have been sitting, but you'll want to pick your spots. THE BOTTOM LINEA 2-1 buydown is a great cushion when you can already afford the full payment. A permanent buydown is the better tool when you plan to keep the loan for the long haul. And sometimes the best move is neither. If you're looking at a home in Middle Tennessee or North Alabama, send me the price and whatever the seller or builder is offering. I'll run the 2-1, the permanent buydown, and a straight price cut side by side so you can see exactly which one does the most for you. Call or text 615-899-CHAD (2423) or 256-509-8200, or email [email protected]. |
Chad Anderson · NMLS #372289 loanDepot.com, LLC · NMLS #174457 · nmlsconsumeraccess.org · Equal Housing Opportunity 840 Crescent Centre Drive, Suite 600, Franklin, TN 37067 Rates referenced are national averages from Freddie Mac's Primary Mortgage Market Survey and are not a quote, offer or commitment to lend. Examples are illustrative, principal and interest only on a 30-year fixed conventional loan with 5% down, and exclude taxes, insurance and mortgage insurance. The permanent buydown example uses a hypothetical rate for illustration only; actual pricing varies by lender, loan and market conditions. Temporary buydowns require qualifying at the full note rate. Buydown availability and seller contribution limits vary by loan program. All loans subject to credit approval and program guidelines. Sources: Freddie Mac PMMS (Oct 1, 2026); Greater Nashville REALTORS (Aug 2026); Huntsville Area Association of REALTORS / ValleyMLS (Aug 2026). |


Facebook
Instagram
X
LinkedIn
Youtube
TikTok
Google Plus